
Variables
Description
What is this formula?
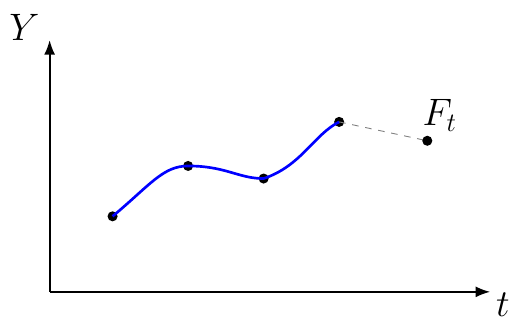
Exponential Smoothing Forecast estimates future values by combining the most recent actual observation with the previous forecast.
The method gives greater importance to recent data while still retaining information from older observations through the previous forecast.
It is one of the most widely used forecasting methods in business, economics, finance, and operations management.
When to use it
Use this formula when historical data does not exhibit strong trends or seasonality and a simple yet effective forecasting method is desired.
Example
Suppose:
Previous Actual Value = 120
Previous Forecast = 110
Smoothing Constant = 0.30
Formula:
Ft=αYt-1+(1−α)Ft-1
Substitution:
Ft=(0.30×120)+(0.70×110)
Ft=36+77
Ft=113
Result:
Forecast for the current period = 113
Applications
Demand forecasting
Sales forecasting
Inventory management
Economic forecasting
Production planning
Business analytics
Note
Exponential Smoothing is an empirical forecasting model rather than an exact mathematical law. The forecast depends strongly on the selected smoothing constant α. Smaller values produce smoother forecasts, while larger values react more rapidly to recent changes. When significant trends or seasonality are present, more advanced methods such as Holt or Holt-Winters forecasting are often preferred.