
Variables
Description
What is this formula?
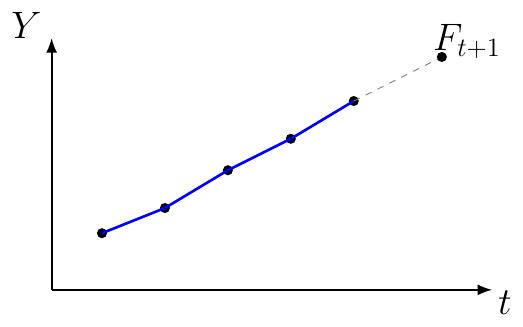
Exponential Smoothing with Trend Forecast, also known as Holt's Method, extends simple exponential smoothing by incorporating an estimate of the trend present in the data.
The forecast is obtained by combining the current smoothed level and the current smoothed trend.
When to use it
Use this method when historical data exhibits a relatively stable upward or downward trend but does not show strong seasonality.
It generally provides more accurate forecasts than simple exponential smoothing when a trend is present.
Example
Suppose:
Smoothed Level = 150
Smoothed Trend = 8
Formula:
Ft+1=Lt+Tt
Substitution:
Ft+1=150+8
Ft+1=158
Result:
Forecast for the next period = 158
Applications
Economic forecasting
Sales forecasting
Demand planning
Inventory management
Production planning
Business analytics
Operations management
Note
This formula represents the forecast stage of Holt's exponential smoothing model. The level and trend estimates are themselves obtained through additional smoothing equations. Forecast quality depends on the selection of smoothing parameters and the stability of the underlying trend. When seasonality exists, Holt-Winters methods are usually preferred.